Running a business can produce strong income, but tax returns don’t always show the full…
Non-QM Loans: Matching Unique Income Situations
Earning enough isn’t always the problem. Proving it through a traditional mortgage file can be. A non-QM loan uses documentation methods outside standard qualified mortgage rules to evaluate a borrower’s ability to repay. In this guide, we’ll explain how we match income patterns with the right loan structure, what lenders review, and where bank statement or DSCR financing may fit.
Key Takeaways
- Purpose: Non-QM loans provide different ways to document income when a traditional mortgage calculation doesn’t reflect the full financial picture.
- Income Options: Depending on the program, qualification may use bank deposits, rental property cash flow, assets, or other documented earnings.
- Requirements: Lenders still review credit, assets, property details, payment history, and the ability to repay.
- Best For: These programs often fit self-employed borrowers, real estate investors, and borrowers with complex or changing income.
Quick Answers About Non-QM Loans
- What makes a non-QM loan different? It allows income documentation and underwriting methods that don’t fit standard qualified mortgage rules.
- Does non-QM automatically mean poor credit? No. Many borrowers have strong credit and assets but earn income in a way that traditional underwriting doesn’t measure well.
- Can a salaried borrower use a non-QM loan? Sometimes. The right program depends on the full scenario, not the borrower’s job title alone.
- How do we choose the documentation method? We review how income is earned, how consistently it appears, and which program presents it most accurately.
At Xie Mortgage Team Powered by NEXA Lending (NMLS# 1660690), we start with the borrower’s actual financial situation. Not a product. Not a shortcut. The goal is to identify the documentation method that fits the income, property, and transaction.
Why Traditional Income Calculations Fall Short
Traditional mortgage underwriting works well when income is stable, salaried, and easy to document. Pay stubs show current earnings. W-2 forms show history. Tax returns generally support the same story.
But many borrowers don’t earn money that way.
A business owner may deduct legitimate expenses that reduce taxable income. A consultant may receive irregular deposits throughout the year. A real estate investor may qualify based on a property’s expected rent rather than personal earnings. Someone moving from contract work to salaried employment may have more than one type of income in the same file.
The borrower may have cash flow. The documents may prove it. But the standard calculation may not capture it.
Non-QM underwriting doesn’t remove documentation. It changes which documentation is used and how the lender evaluates it.
How We Match a Non-QM Loan to the Income
Matching starts with questions. How is the money earned? Where does it get deposited? Is it personal income, business revenue, rental income, or a combination? How long has the pattern existed?
Then we review the transaction itself. Primary residence? Second home? Investment property? Purchase or refinance? The occupancy and property type can change which programs are available.
Our process is borrower-first. We work backward from the facts instead of trying to force every file into the same box.
Step 1: Identify Every Income Source
We separate income by source before discussing loan programs. That may include:
- Salary or hourly earnings
- Business deposits
- Independent contractor or commission income
- Rental property revenue
- Recurring asset distributions
- Documented fixed income
This matters because two borrowers with the same annual cash flow may need completely different documentation. A business owner depositing revenue into a company account is not evaluated the same way as an investor purchasing a rental property.
Step 2: Review the Documentation Trail
Next, we look at what can be documented consistently. Bank statements may show regular business revenue. Lease information and market rent may support an investment property analysis. Asset statements may show funds available for an asset-based calculation.
We also look for issues before underwriting does. Large unexplained deposits. Transfers between accounts. Declining revenue. Overdrafts. Mixed personal and business activity. These details don’t always stop a loan, but they often require explanation or additional records.
Step 3: Compare Available Programs
One program may accept the income but require more reserves. Another may offer a better structure for the property type. A third may not fit because the income history is too short or the documentation doesn’t meet that lender’s rules.
This is where lender differences matter. Non-QM programs are not uniform. Documentation periods, credit standards, reserve requirements, property restrictions, and expense calculations vary by lender.
Step 4: Test the Full File
Income is only one part of qualification. We also review credit, assets, housing history, down payment, property eligibility, and the proposed monthly payment.
The right documentation method still has to support the complete loan file. Finding a program that recognizes the income is useful. Finding one that fits the entire transaction is the actual goal.
Common Non-QM Income Methods Compared
| Documentation Method | Common Scenario | What the Lender Reviews |
|---|---|---|
| Bank statements | Self-employed income that isn’t fully reflected by taxable earnings | Eligible deposits, account activity, business expenses, and income consistency |
| DSCR | Financing an eligible rental property | Property rent compared with qualifying property expenses and debt payments |
| Asset-based calculation | Substantial eligible assets with limited recurring employment income | Eligible asset balances, accessibility, seasoning, and program calculation rules |
| Profit-and-loss documentation | Established business income supported by current operating results | Business history, current revenue, expenses, and required third-party support |
Program availability changes. So do lender requirements. As of 2026, borrowers should verify current documentation periods, reserve standards, rates, fees, and property rules before choosing a loan.
When a Bank Statement Mortgage May Fit
A bank statement mortgage may fit when a self-employed borrower has consistent deposits but tax return income doesn’t represent current cash flow.
The lender generally reviews a required period of personal or business statements. Eligible deposits are identified. Transfers, borrowed funds, and other non-income items are typically excluded. If business statements are used, the lender may apply an expense factor or review supporting business documentation.
This isn’t simply a matter of adding every deposit. Deposit type matters. Account ownership matters. Business expenses matter. The strength of the file depends on a clean, supportable calculation.
For borrowers in Virginia Beach, Chesapeake, Norfolk, Hampton, Newport News, Williamsburg, and Yorktown, our Hampton Roads bank statement loan resource explains the local scenarios we commonly review.
When a DSCR Loan May Fit
A DSCR loan program focuses primarily on an eligible investment property’s rental cash flow. DSCR stands for debt service coverage ratio.
DSCR compares qualifying rental income with the property’s required housing payment or other expenses defined by the program. The exact calculation varies by lender. Some programs use current lease income, appraiser-supported market rent, or a combination of the two.
This structure can help investors separate a property decision from personal tax return income. But the property still has to meet program standards. Credit, reserves, valuation, rent documentation, property condition, and ownership structure may all matter.
Non-QM vs. Conventional, FHA, and VA Loans
Non-QM shouldn’t be the automatic first choice for every complex file. Sometimes the borrower can qualify under conventional, FHA, or VA rules once the income is calculated correctly.
Agency guidelines may allow income that an individual lender won’t accept because of an added overlay. That distinction matters. A lender saying no doesn’t always mean the underlying program says no.
We compare both paths when they are relevant:
- Conventional financing: Often appropriate when documented income meets current agency rules.
- FHA financing: May fit qualifying owner-occupied transactions with its own credit, income, property, and mortgage insurance requirements.
- VA financing: May offer 0% down for eligible borrowers, subject to entitlement, income, credit, occupancy, and property standards.
- Non-QM financing: May fit when the income or property scenario falls outside standard qualified mortgage documentation.
Rates, fees, down payment requirements, and reserve standards vary. The useful comparison is not just monthly payment. It’s the total structure, documentation burden, available cash, and long-term plan.
What Can Make a Non-QM File Stronger?
Clear documentation helps. So does preparation.
- Keep personal and business accounts separate when possible.
- Document large or unusual deposits before submitting the file.
- Avoid moving funds repeatedly between accounts without a clear paper trail.
- Gather complete statements with every page included.
- Review credit early enough to address errors or unresolved accounts.
- Confirm that funds needed for closing and reserves are accessible and properly documented.
- For rental properties, gather leases, insurance information, tax records, and operating expense details.
Direct, transparent, no jargon. We want borrowers to understand what the lender is counting, what it isn’t counting, and why.
Pre-Approval Planning for a Unique Income File
A useful pre-approval starts before a purchase contract. We review documents, compare program rules, and identify conditions that may affect qualification. This is especially important when business accounts, multiple properties, recent credit events, or fluctuating income are involved.
We also discuss tradeoffs. A larger down payment may change available programs. Additional reserves may strengthen the file. Paying off a debt may improve one calculation but reduce the assets needed for closing. Each decision affects something else.
We serve borrowers throughout Hampton Roads and across Virginia, including Northern Virginia, Richmond, Charlottesville, Roanoke, and surrounding markets. We also review eligible scenarios in Birmingham, Indianapolis, and Cleveland. Location matters because property rules, taxes, insurance costs, and conforming loan limits vary by market.
Frequently Asked Questions
Can co-borrowers use different income documentation methods?
Sometimes, depending on the program. A lender may allow one borrower’s salaried income alongside another borrower’s self-employed income, but the accepted documentation and calculation rules vary.
Can non-QM financing be used for different occupancy types?
Many programs cover primary residences, second homes, or investment properties, but not every program allows every occupancy type. DSCR financing is generally designed for eligible investment properties, while other non-QM programs may cover owner-occupied homes.
What happens when business deposits change by season?
Seasonal income may still be considered when the statement history shows a consistent business pattern. The lender may review monthly trends, year-over-year performance, and whether recent deposits support ongoing income.
How long does the non-QM mortgage process take?
Timing depends on the lender, appraisal, property, and complexity of the documentation. Complete statements and early explanations for unusual deposits can reduce avoidable delays, but timelines vary by scenario.
Can a borrower refinance from a non-QM loan later?
Potentially. A future refinance depends on income, credit, equity, property eligibility, market conditions, and the loan programs available at that time.
This is educational and not financial advice. Loan programs and guidelines can change. Talk with a licensed mortgage professional about your specific scenario.
About the Author
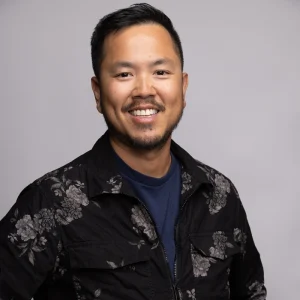
David W. Xie
Senior Mortgage Broker at Xie Mortgage Team Powered by NEXA Lending · NMLS #262139
David Xie is a mortgage broker with 20+ years of experience helping real estate investors and self-employed professionals access DSCR and bank statement loans when traditional lenders say no. NMLS #262139
Specializes in: DSCR loans, Bank statement mortgages, Non-QM lending
Licensed in: VA
Related Posts